
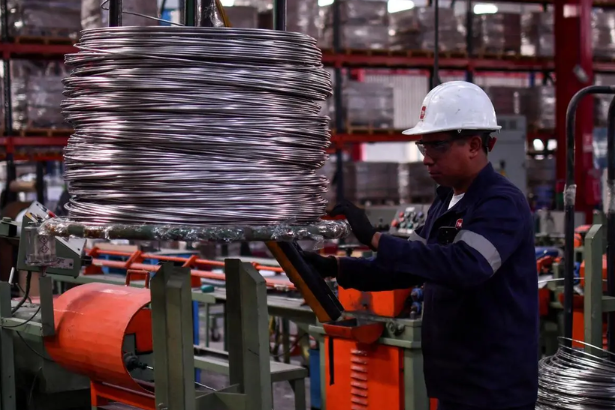
U.S. Manufacturing PMI remained firmly in expansion territory in September, but a sharp increase in factory input prices is giving manufacturers, suppliers and policymakers a new problem to watch.
The Institute for Supply Management’s September report showed the U.S. manufacturing sector expanded for the ninth consecutive month, with the Manufacturing PMI registering 54.5%. The reading was only slightly below August’s 54.6%, but the Prices Index jumped to 77.9% from 71.1%, signaling a much faster increase in raw-material costs.
The result is a complicated picture for American factories. Orders are growing, employment is expanding and backlogs are increasing. At the same time, manufacturers are facing higher prices for metals, fuel, electronics, freight and other critical inputs.
Background and Context
The Manufacturing PMI is one of the closely watched monthly indicators of U.S. factory activity.
A reading above 50 generally indicates that manufacturing activity is expanding, while a reading below 50 indicates contraction. The September reading of 54.5 therefore indicates continued expansion.
The latest number also extends a notable turnaround in the manufacturing sector.
Before the current expansion, U.S. manufacturing had experienced a 10-month period of contraction. September marked the ninth straight month of growth following that downturn.
The headline number, however, does not tell the entire story.
Several underlying indicators improved in September, including new orders, employment and backlogs. Production remained in expansion but slowed from August.
The biggest warning signal was the Prices Index.
At 77.9, it reached its highest level since May and represented a 6.8-point increase from August. ISM reported that raw-material prices increased for the 24th consecutive month.
Latest Update: U.S. Manufacturing PMI Holds at 54.5
The September U.S. Manufacturing PMI came in at 54.5%, just 0.1 percentage point below August’s 54.6%.
The details were more revealing:
| Manufacturing Indicator | September 2026 | August 2026 | Change |
|---|---|---|---|
| Manufacturing PMI | 54.5 | 54.6 | -0.1 |
| New Orders | 55.3 | 53.7 | +1.6 |
| Production | 56.7 | 58.3 | -1.6 |
| Employment | 52.7 | 51.2 | +1.5 |
| Supplier Deliveries | 59.0 | 59.3 | -0.3 |
| Inventories | 48.6 | 50.6 | -2.0 |
| Backlog of Orders | 56.4 | 51.8 | +4.6 |
| Prices | 77.9 | 71.1 | +6.8 |
| New Export Orders | 50.9 | 53.2 | -2.3 |
Source: Institute for Supply Management.
The numbers show that demand remained healthy even as production growth moderated.
New orders increased to 55.3, marking their ninth consecutive month of expansion. Backlogs also rose sharply to 56.4, the highest reading since February according to ISM’s September report.
Factory Employment Moves Higher
The Employment Index rose to 52.7 from 51.2.
That means employment within the manufacturing survey moved further into expansion territory.
The increase is notable because factory hiring has been one of the more closely watched components of the industrial recovery.
It also contrasts with the broader U.S. employment picture, which showed much weaker job growth in September. The Labor Department data released October 2 showed nonfarm payrolls increased by 29,000 and unemployment reached 4.2%.
Manufacturing therefore entered October with its own employment signal that was stronger than the headline national payroll number.
The Biggest Manufacturing Story Is the Prices Index
If the 54.5 PMI represents the good news, the 77.9 Prices Index represents the major pressure point.
The index rose 6.8 points in one month.
ISM said 58.6% of respondents reported paying higher prices for raw materials in September, compared with 46.2% in August. Only 2.8% reported lower prices.
No commodities were reported as down in price in the September survey.
Manufacturers reported higher prices for:
- Aluminum
- Copper
- Electrical components
- Electronic components
- Freight
- Fuel
- Memory components
- Oil-based products
- Packaging materials
- Printed circuit boards
- Resins
- Semiconductors
- Steel
- Zinc
The list shows that the cost pressure is not concentrated in one part of manufacturing.
It stretches across metals, energy, electronics, transportation and packaging.
Read the full September ISM Manufacturing PMI report
Why Rising Input Costs Matter for American Factories
Higher material prices create a difficult calculation for manufacturers.
A factory has several options when its costs increase.
It can absorb the increase and accept lower margins. It can raise prices for customers. It can redesign products around cheaper materials. It can negotiate with suppliers. Or it can delay investment and production decisions.
Each option has consequences.
For manufacturers operating on tight margins, sustained increases in metals, fuel, electronic components and freight can quickly affect profitability.
For companies with stronger pricing power, some of those costs may be passed along to customers.
That creates another potential issue: persistent manufacturing cost inflation can eventually feed into prices elsewhere in the economy.
ISM noted that a Prices Index above 52.8%, over time, is generally consistent with an increase in the Bureau of Labor Statistics’ Producer Price Index for Intermediate Materials.
Tariffs, Energy and Supply Chain Pressures
The September survey also contained reports of uncertainty surrounding trade policy, higher steel and aluminum prices and higher petroleum-related costs.
ISM’s own analysis said the September increase in prices was being driven by higher steel and aluminum prices, tariffs on imported goods and increases in petroleum-based products connected with the Middle East conflict.
These factors matter because modern manufacturing is deeply connected to global supply chains.
A U.S. factory may purchase steel domestically, source electronic components internationally, rely on imported machinery and use diesel-powered transportation to move finished products.
A price increase at several points in that chain can compound the final cost.
The September ISM survey also identified shortages involving aluminum products, copper, DRAM, electrical components, electronic components, memory, printed circuit boards, steel and tungsten products.
That combination of rising prices and shortages is particularly important for industries dependent on electronics and advanced manufacturing.
AI Is Helping Support Factory Demand
The manufacturing expansion is not happening in isolation.
Reuters reported that demand linked to AI infrastructure development and inventory rebuilding was helping support U.S. manufacturing activity.
The broader global manufacturing picture also shows strong demand for AI-related equipment.
Reuters reported that factory activity in Europe and Asia was benefiting from increased demand for AI infrastructure, semiconductors and related capital goods.
For U.S. manufacturers, this creates an important source of demand.
AI infrastructure requires enormous quantities of physical equipment, including servers, electrical components, semiconductors, cooling systems, networking equipment and power infrastructure.
That demand can flow through multiple layers of the manufacturing supply chain.
Expert Insights and Analysis
The September data suggests that the U.S. manufacturing recovery is continuing, but it is becoming more expensive.
That distinction matters.
A manufacturing sector can expand while manufacturers simultaneously experience margin pressure.
The September data provides several examples.
Demand is improving. New orders increased for the ninth straight month.
Backlogs are growing. The Backlog of Orders Index increased to 56.4.
Employment is expanding. The Employment Index reached 52.7.
Production remains strong. The Production Index remained at 56.7.
But:
Input prices are accelerating. The Prices Index jumped to 77.9.
Inventories are contracting. The Inventories Index dropped below 50 to 48.6.
Supplier deliveries remain slow. The Supplier Deliveries Index was 59.0, where a reading above 50 indicates slower deliveries.
Together, those numbers describe a manufacturing sector with solid demand but increasing operational friction.
ISM itself noted that sentiment among survey respondents remained considerably more negative than the underlying data.
Its September report said 40% of comments were positive and 60% negative, with pricing volatility, tariffs and geopolitical uncertainty among the major sources of concern.
That disconnect between business sentiment and manufacturing activity is worth watching.
What the Manufacturing PMI Means for Supply Chains
The September numbers also have implications beyond factory floors.
When manufacturers report higher prices for steel, aluminum, copper, semiconductors and electrical components, the impact can move through the entire supply chain.
Consider a manufacturer producing industrial equipment.
Higher steel prices increase material costs.
Higher semiconductor prices increase electronic component costs.
Higher freight and fuel prices raise transportation expenses.
If inventories are low, manufacturers may have less flexibility to wait for cheaper materials.
If customer demand remains strong, companies may continue ordering despite those higher costs.
This can create a feedback loop in which strong demand keeps factories busy while limited supplies and higher input costs put upward pressure on prices.
The ISM report showed customer inventories remained “too low,” with the Customers’ Inventories Index at 41.6, its 24th consecutive month in that territory.
Broader Implications for U.S. Manufacturing
The September report leaves several major questions for American industry.
Will manufacturers continue hiring?
The Employment Index increased to 52.7, suggesting expansion in factory employment in the ISM survey.
Whether that momentum continues will depend partly on order volumes, production requirements and companies’ response to higher costs.
Can manufacturers absorb higher material costs?
That will vary significantly by industry and company.
Businesses with strong demand and pricing power may be better positioned to pass costs through. Others may face pressure on margins.
Will supply shortages become more widespread?
The September survey identified shortages across several electronics and metal categories.
If those shortages persist while demand remains strong, lead times and costs could remain elevated.
Will manufacturing investment continue?
Growing backlogs and strong new orders can encourage investment.
But uncertainty around costs can have the opposite effect.
ISM highlighted comments from manufacturers indicating that some customers were delaying capital expenditures because of uncertainty over costs and demand.
That tension could become increasingly important in the final months of 2026.
For more coverage of business, technology and industrial trends, visit The Tech Marketer.
Related History and Comparable Manufacturing Cycles
The current manufacturing expansion follows a period of contraction.
ISM’s September data shows the sector entered its ninth consecutive month of expansion after a 10-month period in contraction.
The recovery has therefore been significant, but it has not been uniform.
The 12-month PMI series shows manufacturing moving from readings below 50 in October, November and December 2025 into sustained expansion during 2026.
| Month | Manufacturing PMI |
|---|---|
| October 2025 | 48.8 |
| November 2025 | 48.0 |
| December 2025 | 47.9 |
| January 2026 | 52.6 |
| February 2026 | 52.4 |
| March 2026 | 52.7 |
| April 2026 | 52.7 |
| May 2026 | 54.0 |
| June 2026 | 53.3 |
| July 2026 | 55.6 |
| August 2026 | 54.6 |
| September 2026 | 54.5 |
Source: ISM.
The progression shows why September’s 54.5 reading matters.
It is not an isolated increase. It is part of a sustained recovery that began at the start of 2026.
The challenge now is whether that expansion can continue while input-cost pressures rise.
What Happens Next for U.S. Manufacturing?
The October manufacturing data will be closely watched for evidence of whether September’s price acceleration was temporary or part of a broader trend.
Manufacturers will also be watching:
- New orders
- Production
- Employment
- Backlogs
- Supplier delivery times
- Raw-material prices
- Customer inventories
- Export orders
- Semiconductor availability
- Steel and aluminum costs
- Freight and fuel prices
The Federal Reserve will also have an interest in the inflation implications of manufacturing costs.
The ISM report noted that the Prices Index reached 77.9, while Reuters reported that the increase in factory input prices added to concerns about persistent inflation pressures.
At the same time, the manufacturing sector continues to show genuine signs of demand.
New orders are growing. Backlogs are expanding. Employment is increasing.
That means the next phase of the manufacturing story is unlikely to be defined simply by expansion versus contraction.
Instead, the key question is whether American factories can maintain growth while controlling the cost of producing goods.
Conclusion
The U.S. Manufacturing PMI delivered a mixed but important message for September 2026.
At 54.5, the index shows that American manufacturing remained in expansion for the ninth consecutive month. New orders rose, backlogs increased and the employment index moved higher.
But the sharp jump in the Prices Index to 77.9 changes the conversation.
Manufacturers reported higher costs for metals, electronics, fuel, freight, packaging and other critical inputs. Several categories were also reported in short supply.
For U.S. factories, the recovery is therefore entering a more complicated phase.
Demand remains strong enough to support expansion, but the cost of satisfying that demand is rising.
The coming months will show whether manufacturers can convert strong orders and backlogs into sustained production and employment growth without allowing higher input costs to undermine margins and push prices higher across the broader economy.
FAQ
What was the U.S. Manufacturing PMI in September 2026?
The U.S. Manufacturing PMI was 54.5% in September 2026, down slightly from 54.6% in August. The reading marked the ninth consecutive month of manufacturing expansion.
Why did the U.S. Manufacturing PMI remain above 50?
New orders, production and employment remained in expansion territory. New orders increased to 55.3, production was 56.7 and employment reached 52.7.
What does the ISM Prices Index of 77.9 mean?
The ISM Prices Index measures the direction of raw-material prices reported by manufacturers. A reading of 77.9 indicates that prices were increasing significantly, and the September reading was 6.8 points higher than August.
Which manufacturing materials became more expensive?
ISM respondents reported higher prices for aluminum, copper, electrical components, electronic components, freight, fuel, memory components, semiconductors, steel, packaging materials and several other inputs.
Are U.S. manufacturing jobs increasing?
The ISM Manufacturing Employment Index increased from 51.2 in August to 52.7 in September, indicating expansion in the survey’s employment measure.
What is the biggest concern for American manufacturers?
The September data points to rising input costs, supply shortages and uncertainty as major concerns. ISM reported higher prices across numerous commodities and shortages involving several electronics and metal categories.
How long has U.S. manufacturing been expanding?
The U.S. manufacturing sector expanded for the ninth consecutive month in September 2026 after a 10-month period of contraction.
SOURCES & REFERENCES
- September 2026 ISM Manufacturing PMI Report, Institute for Supply Management
Read the official ISM report - ISM PMI Reports Roundup: September Manufacturing, Institute for Supply Management
Read the ISM analysis - U.S. manufacturing steady in September, input prices increase, Reuters
Read the Reuters report - Manufacturing PMI at 54.5%, September 2026 ISM Manufacturing PMI Report
Read the report release