
Introduction
U.S. ocean freight is entering an unusual late-summer stretch. After the National Retail Federation and Hackett Associates previously expected the 2026 peak season to wind down, their September forecast now points to another surge in imports. Major U.S. container ports are expected to handle approximately 2.31 million TEUs in September, which would make it the busiest month of the year and represent a 9.6% increase from September 2025.
At the same time, ocean freight pricing remains elevated. Freightos reported Asia-to-U.S. West Coast spot rates of about $7,569 per 40-foot equivalent unit in its September 8 update, while Reuters reported a much sharper increase in China-to-U.S. East Coast rates later in the month, with spot prices reaching $10,948 per 40-foot container amid rising fuel costs.
The combination creates a complicated peak season. Importers are moving large volumes, but getting those goods across the ocean is becoming more expensive and more sensitive to disruptions.
Background and Context
The traditional U.S. ocean freight peak season usually builds toward the final months of the year as retailers prepare for back-to-school sales, Halloween, Thanksgiving and the Christmas shopping season.
But 2026 has followed a different pattern.
Retailers and other importers brought merchandise forward earlier in the year because of uncertainty surrounding tariffs, fuel prices and geopolitical disruptions. In July, the NRF forecast that imports could reach a record monthly level as businesses moved goods into the country ahead of potential tariff increases.
By August, the expectation was that the early peak would begin fading.
That did not happen as quickly as expected.
The latest Global Port Tracker forecast says September could now edge ahead of July’s 2.3 million TEU and become the year’s busiest month. The report forecasts 2.31 million TEU in September, followed by 2.11 million in October and 2 million in November.
That means the 2026 peak season has effectively stretched across multiple periods rather than producing one short surge.
Latest Update: U.S. Ocean Freight Volumes Surge Into September
The latest numbers from the NRF provide the clearest indication of how unusual the current shipping season has become.
U.S. container ports covered by the Global Port Tracker handled 2.3 million TEUs in July, down 3.9% from the same month a year earlier but up 3.2% from June.
September is forecast at 2.31 million TEUs, up 9.6% year over year. If that forecast holds, September will slightly surpass July and become the busiest import month of 2026.
The forecast also puts total U.S. port imports for 2026 at approximately 25.7 million TEUs, about 1% above 2025’s 25.4 million TEUs.
NRF’s September 2026 import forecast
U.S. import outlook
| Month | Forecast imports | Year-over-year change |
|---|---|---|
| July | 2.30 million TEU actual | -3.9% |
| August | 2.29 million TEU forecast | -1.3% |
| September | 2.31 million TEU forecast | +9.6% |
| October | 2.11 million TEU forecast | +1.7% |
| November | 2.00 million TEU forecast | -0.9% |
| December | 2.03 million TEU forecast | +1.1% |
| 2026 total | 25.7 million TEU | +1.0% |
Source: NRF and Hackett Associates Global Port Tracker.
The numbers show that the U.S. import market is not experiencing a simple boom or bust. Instead, businesses are moving cargo around the calendar in response to tariffs, weather, consumer demand and transportation uncertainty.
Why September Became So Important
Several factors are contributing to the extended peak.
Weather disruptions in China
The NRF says vessel delays caused by bad weather in China have shifted some cargo movement into September.
S&P Global similarly reports that typhoons affecting key Chinese loading ports contributed to delays and helped extend the U.S. import peak.
When vessels are delayed at origin ports, the effect does not stop there. A delayed vessel can create bunching at terminals, alter sailing schedules and disrupt downstream warehouse and trucking plans.
Panama Canal restrictions
The Panama Canal is another factor.
The NRF says some vessels have been rerouted away from the canal because of potential drought-related restrictions.
Reuters has also reported growing stress around Panama Canal capacity, with increased demand from energy shipments adding pressure to available transit slots. The company says container volumes typically rise between August and October as retailers prepare for the holiday season.
For shippers, that creates another potential source of delays and additional transportation costs.
Tariff uncertainty
Tariff changes have also encouraged businesses to move cargo earlier than they otherwise might have.
The result is an important change in logistics planning.
Instead of simply asking when consumers will need the goods, importers increasingly have to ask when it is financially and operationally safest to bring the goods into the United States.
Ocean Freight Rates Remain Elevated
Higher import volumes would normally create upward pressure on container prices, although capacity additions can offset some of that effect.
That is broadly what happened earlier in September.
Supply Chain Dive, citing the Freightos Baltic Index, reported that Asia-to-U.S. West Coast spot rates fell 1% week over week to $7,569 per FEU as of the September 8 update. East Coast rates fell 3% to approximately $9,505 per FEU.
Supply Chain Dive’s ocean freight rate analysis
But the rate picture changed rapidly.
Reuters reported on September 17 that China-to-U.S. East Coast container rates had climbed to $10,948 per 40-foot container, with analysts warning that rates could test pandemic-era records. The report attributed the latest pressure partly to soaring fuel costs connected to the conflict involving Iran and disruptions around key energy routes.
This illustrates an important point about U.S. ocean freight rates in 2026: a single weekly rate snapshot may become outdated quickly when fuel costs, geopolitical disruptions and seasonal demand are changing simultaneously.
The Port of Los Angeles Shows the Scale of the Surge
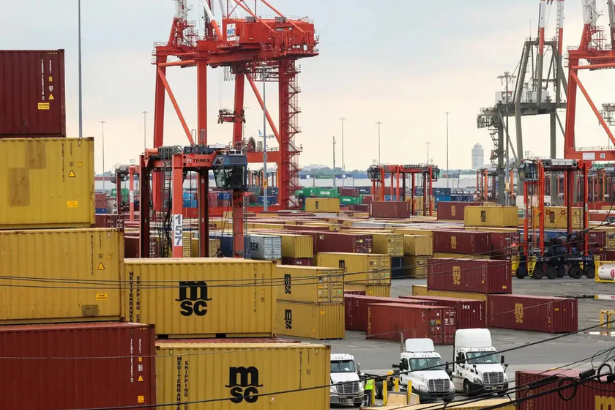
The Port of Los Angeles provides another indication of how strong the recent import wave has been.
Reuters reported that the port handled 2.9 million TEUs during June, July and August, marking a record three-month period for the port. August alone reached 955,907 TEUs, exceeding the previous peak recorded during the pandemic-era shipping boom.
Retailers have been bringing holiday merchandise into the country earlier in an effort to manage tariff exposure and other costs.
That means containers arriving now may contain products that will not reach consumers for weeks or months.
The port surge is therefore not simply a reflection of immediate consumer demand. It is also a reflection of how businesses are managing uncertainty.
What This Means for Holiday Inventory
For retailers, the September import surge has a direct connection to the holiday season.
Products arriving through U.S. ports now can move into distribution centers before the major November and December shopping period.
That creates a potential advantage for retailers that have successfully secured inventory, but it also creates new challenges.
More inventory means:
- Greater warehouse requirements
- Higher inventory carrying costs
- More inland transportation demand
- Greater exposure to storage costs
- Increased working-capital requirements
- More pressure on distribution networks
The NRF expects imports to fall after September, with October forecast at 2.11 million TEUs and November at 2 million.
That means September could represent the final major import push before the shipping calendar begins to normalize.
Expert Insights and Analysis
The current market is best understood as a collision between strong cargo demand and constrained logistics flexibility.
NRF Vice President for Supply Chain and Customs Policy Jonathan Gold said the organization had expected peak season to be mostly over but now expects another September bump. The NRF attributed part of the shift to vessel delays in China and rerouting around the Panama Canal, while also noting that consumers continue to buy despite tariffs, inflation and high fuel prices.
Ben Hackett of Hackett Associates similarly said imports have remained buoyant despite tariffs and higher fuel costs, while noting reports of vessel delays and longer cargo transit times.
The rate picture adds another dimension.
Freightos showed modest cooling in early September, while Reuters documented a later surge in East Coast rates.
Together, those developments suggest that freight pricing is becoming increasingly dependent on route, timing and disruption exposure.
A retailer shipping through the U.S. West Coast may face a different cost environment from one relying on the East Coast. A company booking cargo before a disruption may also pay substantially less than one trying to secure capacity afterward.
Broader Implications for U.S. Supply Chains
The current U.S. ocean freight environment has implications beyond ports and shipping companies.
Retail
Retailers need inventory in place before the holiday season, but importing too early can increase storage and financing costs.
Manufacturing
Manufacturers that depend on imported components face additional uncertainty around lead times and transportation costs.
E-commerce
Online retailers must account for ocean freight costs when calculating landed product costs and margins.
Warehousing
A late import surge can create uneven demand for warehouse space, especially in major distribution hubs.
Trucking and rail
Once containers leave the ports, the additional volume moves into inland transportation networks. A large import wave can therefore affect truck and rail capacity even when the initial disruption occurs at sea.
This is why port data are increasingly useful as an early indicator for the wider U.S. logistics market.
Internal link suggestion: How AI Is Transforming U.S. Supply Chain Management in 2026 → https://thetechmarketer.com/
Related History or Comparable Technologies
The current peak season is not the first time U.S. importers have shifted cargo forward.
The COVID-era supply-chain crisis demonstrated how quickly container demand, port congestion and freight rates can move together.
The difference in 2026 is that businesses are dealing with a broader collection of variables.
Today’s import decisions can be influenced by:
- Tariff announcements
- Fuel prices
- Geopolitical disruptions
- Weather
- Canal restrictions
- Port congestion
- Consumer demand
- Warehouse availability
- Carrier capacity
Technology is increasingly being used to manage this complexity.
Modern transportation management systems can combine carrier schedules, estimated arrival times, inventory levels and transportation costs. Predictive analytics can then help logistics teams identify potential disruptions before cargo reaches a U.S. port.
That is becoming particularly valuable when shipping conditions can change in a matter of days.
What Happens Next?
The next major question is whether September’s import surge is temporary or whether elevated volumes continue into October.
The current NRF forecast points toward a decline after September:
- October: 2.11 million TEUs
- November: 2 million TEUs
- December: 2.03 million TEUs
- January 2027: 2.09 million TEUs
The organization expects 2026 total imports at approximately 25.7 million TEUs.
Freight rates are the other major variable.
The early September Freightos data showed modest cooling, but Reuters’ later report showed significant East Coast rate increases linked to fuel and geopolitical pressures.
That means businesses cannot assume that a seasonal decline in U.S. import volumes will automatically produce cheaper freight.
Fuel costs, vessel capacity, route disruptions and geopolitical events can overwhelm normal seasonal patterns.
Key Numbers to Watch
| Indicator | Current / Forecast Figure |
|---|---|
| September U.S. imports | 2.31 million TEU |
| September YoY change | +9.6% |
| July U.S. imports | 2.30 million TEU |
| 2026 projected imports | 25.7 million TEU |
| Asia to U.S. West Coast rate, Sept. 8 | $7,569/FEU |
| Asia to U.S. East Coast rate, Sept. 8 | $9,505/FEU |
| China to U.S. East Coast rate reported Sept. 17 | $10,948/40-foot container |
| Port of Los Angeles June-August volume | 2.9 million TEU |
| Port of Los Angeles August volume | 955,907 TEU |
Sources: NRF, Freightos, Supply Chain Dive and Reuters.
Conclusion
The U.S. ocean freight market is entering September with an unusual combination of high import volumes, elevated freight costs and continuing supply-chain uncertainty.
The latest NRF forecast puts September U.S. port imports at 2.31 million TEUs, potentially making it the busiest month of 2026. That follows a year in which retailers and manufacturers repeatedly adjusted shipping schedules in response to tariffs, fuel costs, weather disruptions and geopolitical risks.
Freight rates tell an equally complicated story. Early September data showed some cooling, but later Reuters reporting showed China-to-U.S. East Coast rates approaching $11,000 per 40-foot container as fuel and geopolitical pressures intensified.
For U.S. importers, the lesson is not simply that peak season is busy.
It is that timing has become one of the most important variables in logistics.
The cost of moving a container can change depending on when it is booked, which route it takes, whether a vessel is delayed and what is happening with fuel and global trade conditions.
As September cargo moves through U.S. ports and retailers prepare for the holiday season, those variables will remain closely watched across the entire supply chain.
FAQ
What is happening with U.S. ocean freight in September 2026?
U.S. import volumes are expected to reach approximately 2.31 million TEUs in September, which would make it the busiest month of 2026 according to the NRF and Hackett Associates Global Port Tracker.
Why are U.S. imports increasing in September?
The extended peak season has been influenced by vessel delays caused by weather in China, Panama Canal routing issues, tariff uncertainty and continued consumer demand.
Are ocean freight rates going up?
Rates have been volatile. Freightos reported a slight decline in early September, while Reuters reported a significant increase in China-to-U.S. East Coast rates later in the month.
What are current Asia-to-U.S. ocean freight rates?
Freightos reported approximately $7,569 per FEU from Asia to the U.S. West Coast and approximately $9,505 per FEU to the U.S. East Coast in its September 8 update. Reuters subsequently reported $10,948 per 40-foot container on the China-to-U.S. East Coast route on September 17.
Why is September important for U.S. retailers?
September cargo can replenish inventories ahead of the holiday shopping season. Retailers have also been bringing goods forward to manage tariff and transportation uncertainty.
Could freight rates fall after peak season?
They could, but seasonal demand is only one factor. Fuel prices, vessel capacity, geopolitical disruptions, port congestion and canal restrictions can all affect rates independently of normal seasonal patterns.
What does the import surge mean for U.S. supply chains?
Higher import volumes can increase demand for port handling, warehouses, trucking and rail transportation. It can also create higher inventory carrying costs for retailers that bring goods into the country well ahead of final consumer demand.
Sources & References
- National Retail Federation, “Import Cargo’s Peak Season Not Over Yet”
Read the NRF report - S&P Global, “US retailers expect September to be busiest month of year for imports”
Read the S&P Global analysis - Supply Chain Dive, “Ocean freight rates cool despite continued price elevation”
Read the Supply Chain Dive report - Reuters, “Ocean container shipping rates could test record highs as Iran war fuel spike drives rise”
Read the Reuters report - Reuters, “Busiest US seaport set new three-month volume record after early holiday import rush”
Read the Reuters report