
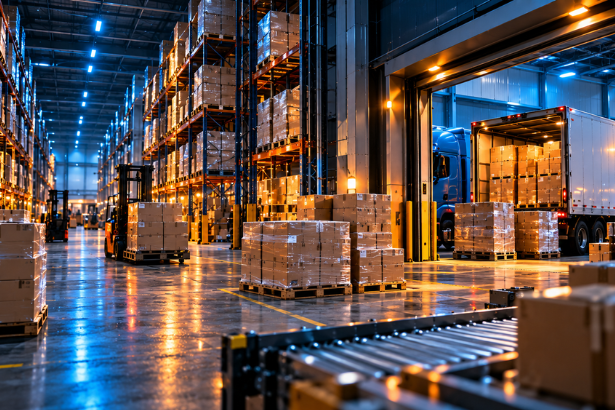
U.S. supply chain pressures are building as companies prepare for peak-season demand. The September 2026 Logistics Managers’ Index (LMI) climbed to 70.2, its second-highest reading in four years, as inventory levels expanded and warehouse and transportation capacity contracted. The figures point to a difficult equation for manufacturers, distributors and retailers: more products are entering the system just as storage space and freight availability become harder to secure. Source: September 2026 Logistics Managers’ Index
The immediate concern is the holiday shopping period, when companies typically move goods from wholesalers and distribution centers toward stores and consumers. Inventory built up earlier in the year now has to move through a logistics network facing higher costs and tighter capacity.
For businesses, this is a test of planning as much as purchasing. Companies that forecast demand carefully, reserve logistics capacity early and avoid relying on a single supplier or shipping route may be better positioned to handle the squeeze.
Background and Context: Why Supply Chains Are Feeling the Pressure
The Logistics Managers’ Index tracks eight components of the logistics industry, including inventory levels and costs, warehouse capacity and prices, and transportation capacity and prices. A reading above 50 indicates expansion, while a reading below 50 indicates contraction.
The overall index reached 70.2 in September, up from 66.6 in August. But the headline figure only tells part of the story. Inventory levels rose as storage and transportation capacity became more constrained, creating a mismatch between the amount of goods companies want to move and the resources available to handle them. Read the full September LMI report
The key figures show how quickly conditions changed:
| Logistics metric | September 2026 reading | What it signals |
|---|---|---|
| Overall Logistics Managers’ Index | 70.2 | Logistics activity is expanding rapidly |
| Inventory Levels | 58.9 | Inventory is growing |
| Inventory Costs | 79.9 | The cost of holding inventory remains elevated |
| Warehousing Capacity | 39.3 | Available warehouse capacity is contracting |
| Warehousing Utilization | 64.3 | More warehouse space is being used |
| Warehousing Prices | 73.5 | Warehouse pricing continues to rise |
| Transportation Capacity | 34.4 | Available freight capacity is contracting |
| Transportation Prices | 92.7 | Transportation costs are increasing sharply |
Source: September 2026 Logistics Managers’ Index. The LMI is a diffusion index, so readings below 50 indicate contraction in the measured metric, not that the metric itself has reached zero.
The contrast is especially important. Inventory levels are expanding, but warehouse capacity is contracting. Transportation capacity is also tightening, while transportation prices are rising at a much faster rate than the overall index.
This does not automatically mean every company will face shortages or delays. Conditions vary by region, product category, carrier, warehouse provider and shipping lane. But the national picture suggests that businesses should not assume storage or freight will be readily available when they need it.
Latest Update: Inventory Is Growing as Warehouse and Freight Capacity Tighten
Source Logistics’ October 2026 market update describes a seasonal transition now taking shape: holiday inventory that has been sitting with wholesalers and distributors is beginning to move toward retailers, at a time when the logistics network has less spare capacity.
The LMI data supports that picture. Inventory levels increased 6.1 points to 58.9 in September. Wholesalers and distributors reported faster inventory growth, with an index reading of 61.4, compared with 53.8 for retailers. That gap suggests that a substantial amount of product was still positioned upstream in the supply chain before the usual seasonal transfer to retail locations.
The challenge is that the handoff itself requires space, labor, dock appointments, trucks and careful coordination. When several companies try to move goods at once, a plan that looks manageable on paper can quickly become expensive in practice.
Warehouse capacity is shrinking
Warehousing Capacity fell 14.2 points to 39.3, marking the fastest contraction since March 2022, according to the September LMI. At the same time, warehouse utilization rose to 64.3 and warehousing prices remained in expansion territory at 73.5. LMI report
The implications are not limited to large retailers. Smaller businesses can be particularly exposed because they may have less bargaining power when negotiating warehouse space or reserving additional capacity during peak season.
The Source Logistics update also points to weaker additions to new industrial warehouse supply. Citing CBRE data, it reports that second-quarter completions fell to 47.9 million square feet, the lowest quarterly total since 2016. New buildings cannot provide an immediate fix when demand for usable space is rising now.
Freight capacity is tightening too
The transportation market is showing similar stress. The September LMI recorded transportation capacity at 34.4 and transportation prices at 92.7. In its October 6 coverage, FreightWaves reported that transportation prices surged as capacity tightened.
When trucks are harder to secure, shippers may have to pay more, accept less convenient pickup times or adjust delivery schedules. Refrigerated freight, time-sensitive shipments and routes with limited carrier options can present additional challenges.
For companies moving food, beverages, seasonal merchandise or other products with strict delivery windows, logistics planning needs to include the full journey from inbound receipt to final delivery, not just the cost of the initial shipment.
The demand picture remains uncertain
There is another complication: companies are preparing for holiday demand without knowing exactly how much consumers will spend. The September LMI report points to weaker consumer confidence and continued uncertainty about the strength of fourth-quarter demand. At the same time, inventory costs remain high.
That combination creates a risk on both sides. Under-ordering could leave businesses unable to meet demand. Over-ordering could leave them paying for storage and transportation while unsold goods tie up working capital.
The goal is not simply to stock more. It is to make inventory decisions that account for demand uncertainty and the cost of moving and holding products.
Why Businesses Are Building Inventory Ahead of Peak Season
Inventory growth is not necessarily a sign that companies have lost control of their supply chains. In many cases, building stock ahead of peak season is a deliberate way to protect sales and reduce exposure to delays.
Several forces are shaping these decisions.
1. Seasonal demand arrives on a predictable calendar. Retailers and consumer brands need products available before holiday promotions, not after orders start coming in. Building inventory early gives companies time to receive, inspect, package and distribute goods before demand peaks.
2. Import timing can be unpredictable. International shipping involves port congestion, customs processing, inland transportation and other potential delays. Companies that depend on overseas suppliers may bring inventory forward to create a buffer against disruptions.
3. Tariffs complicate purchasing decisions. Uncertainty over duties and trade policy can change the expected cost of imported goods. Some businesses may choose to purchase earlier to reduce exposure to possible cost changes. But that strategy carries risks if policy changes, demand weakens or storage costs rise.
4. Businesses want to avoid stockouts. A product that arrives late can miss a promotional window or leave shelves empty. For some categories, the lost sale and damage to customer loyalty may cost more than carrying additional stock.
The difficulty is that these decisions are often made independently. When many companies order early at the same time, their combined demand for warehouse space and transportation can strain the logistics network.
That is the central lesson of the September LMI: a company can make a sensible decision to increase inventory and still encounter trouble if it has not secured the capacity to store and distribute that inventory.
Expert Analysis: The Cost of Holding Inventory Is More Than the Purchase Price
Inventory is often treated as a purchasing decision. In a constrained logistics market, it is a broader financial commitment.
Each additional pallet can generate costs for storage, handling, insurance, financing, shrinkage and eventual delivery. If demand slows, those costs continue even when the product is not selling. If goods must be moved urgently, the company may also pay more for expedited transportation or last-minute warehouse arrangements.
The September LMI put Inventory Costs at 79.9, while the aggregate reading for inventory, warehousing and transportation costs reached 246.1, according to the report. These are index readings rather than dollar amounts, but they indicate that several cost pressures are occurring at once. September 2026 LMI
For supply chain leaders, the more useful question is not simply, “How much inventory should we buy?” It is, “What is the total cost of having this inventory available at the right place and time?”
That requires connecting purchasing decisions to logistics capacity, customer demand and cash flow.
Tariff uncertainty makes the calculation harder
Trade-policy uncertainty can create incentives to buy early, shift suppliers or change sourcing locations. Yet buying ahead of a potential tariff change is not automatically the best financial move.
A business should compare the potential tariff exposure against the cost of carrying extra inventory, the risk of a policy reversal, the likelihood of demand changes and the availability of alternative suppliers. It should also consider whether a supplier can deliver reliably when orders are placed later.
A useful decision framework compares at least three scenarios:
- Buy early: More inventory is secured now, but the business assumes storage and working-capital costs.
- Buy closer to demand: Inventory holding costs may be lower, but the company risks higher prices or longer lead times.
- Diversify sourcing: The business reduces dependence on a single supplier or country, but may incur qualification, freight or coordination costs.
The right choice depends on product criticality, shelf life, supplier lead times, margins and the business’s ability to absorb disruption. A uniform policy across all products is unlikely to work well.
Broader Implications: The Inventory Problem Is Also a Resilience Problem
The current squeeze exposes a weakness in supply chain strategies that prioritize low inventory above almost everything else. Lean inventory can reduce carrying costs, but it also leaves less room to absorb a late shipment, a demand spike or a temporary loss of warehouse or freight capacity.
The opposite approach, holding large buffers for every product, is expensive and can create excess stock. Resilience requires a more selective strategy: identify which products need protection, where flexibility matters most and which disruptions would be most costly.
For executives, that means bringing procurement, sales, operations, finance and logistics teams into the same planning process. Purchasing teams need visibility into warehouse availability. Sales teams need to share updated demand forecasts. Finance teams need to understand the cash tied up in stock. Logistics teams need to know what is arriving, when it will arrive and how quickly it must move.
This is also an opportunity to revisit the technology supporting supply chain decisions. Inventory management systems, demand forecasting tools and transport management platforms can help teams identify bottlenecks sooner, but only if the underlying data is current and the teams use consistent assumptions.
Internal link suggestion for The Tech Marketer: Add a contextual link to a related article on The Tech Marketer about AI-powered supply chain forecasting, warehouse automation or enterprise inventory management. Suggested anchor text: how AI is changing supply chain planning.
The strategic shift is from treating inventory as a standalone asset to managing it as part of an end-to-end network. A business needs to know not only what it owns, but where it is, how much it costs to hold, and whether it can reach customers on time.
Practical Strategies for Inventory Planning and Supplier Diversification
Companies do not need to predict every market move to improve their position. They need a process that makes risks visible early and provides options when conditions change.
1. Segment inventory by business importance
Not every product deserves the same buffer. Classify items by sales value, demand variability, lead time, margin, shelf life and how damaging a stockout would be.
- Critical products: Maintain carefully calculated safety stock where replenishment is slow or a stockout would halt operations.
- High-volume seasonal products: Align purchase timing with promotion dates, inbound schedules and confirmed warehouse capacity.
- Slow-moving or uncertain products: Use smaller commitments, more frequent reviews or staged purchasing where suppliers allow it.
- Perishable or time-sensitive goods: Prioritize shelf life, temperature control and delivery reliability over simply maximizing stock availability.
This approach directs working capital toward products where extra inventory offers the greatest protection.
2. Link forecasts to actual logistics capacity
A demand forecast is incomplete if it assumes unlimited space and transportation.
For every major inbound order, teams should confirm expected arrival dates, warehouse receiving windows, available storage, labor requirements and outbound transportation. Scenario planning should account for delayed arrivals, faster-than-expected sales and a weaker-than-expected holiday season.
A simple dashboard can track:
| Metric | Why it matters |
|---|---|
| Inventory days on hand | Shows how long current stock is expected to last |
| Forecast accuracy | Reveals where demand assumptions are consistently wrong |
| Supplier lead-time variability | Helps estimate the buffer needed for replenishment |
| Warehouse utilization | Flags space constraints before overflow becomes urgent |
| On-time, in-full delivery | Measures whether suppliers meet agreed service levels |
| Freight cost per unit | Shows whether transport costs are eroding product margins |
| Aged or slow-moving stock | Identifies inventory at risk of tying up cash after peak season |
The objective is to spot a capacity problem while there is still time to respond, not when a truck arrives and the warehouse has nowhere to put the goods.
3. Reserve flexible warehouse capacity early
Businesses expecting seasonal surges should evaluate warehouse requirements before the market becomes more constrained. Options may include short-term overflow space, shared warehousing, third-party logistics providers and distribution arrangements closer to major customer markets.
Contracts should be reviewed carefully. A low headline rate may not include handling, labor, minimum volume commitments, peak-season surcharges or the cost of moving inventory between facilities.
Flexibility matters as much as price. A business should understand how quickly it can add space, reduce its footprint after the holidays and transfer stock if a facility becomes unavailable.
4. Diversify suppliers with a clear purpose
Supplier diversification can reduce dependence on a single source, region or transportation route. But adding suppliers creates work and does not automatically make the supply chain more resilient.
Before qualifying an alternative supplier, assess product quality, production capacity, lead times, compliance requirements, freight routes, payment terms and the supplier’s own exposure to tariffs or material shortages.
A practical approach is to identify the products with the greatest disruption risk and qualify backup suppliers for those items first. For important components, businesses may also consider dual sourcing or maintaining a second approved manufacturing location.
The goal is not to replace one dependency with several poorly understood ones. It is to create credible alternatives that can actually deliver when needed.
5. Model tariff scenarios instead of reacting to headlines
Trade policy can change sourcing economics, but companies should avoid basing major inventory commitments on a single assumed outcome.
Procurement and finance teams can model multiple tariff scenarios and calculate the resulting landed cost for each supplier. The model should include product price, duties, freight, insurance, handling, inventory carrying cost and expected delivery performance.
Review the scenarios when official policy changes or supplier quotes are updated. This helps distinguish a genuine cost advantage from a temporary incentive to order early.
6. Build a plan for the post-holiday inventory hangover
Peak-season planning should include a clear exit strategy. If demand falls short, excess stock can continue to consume warehouse space and working capital well into the new year.
Businesses should define in advance how they will handle slow-moving stock, markdowns, returns, transfers between locations and the release of temporary warehouse capacity. Forecasts should be updated as actual sales data arrives rather than leaving the original plan untouched.
This matters because buying enough inventory to meet holiday demand is only half the problem. Companies also need to avoid carrying the wrong inventory long after the demand window closes.
Related History: Lessons From Earlier Supply Chain Disruptions
The latest capacity squeeze is not the first time companies have had to balance inventory against logistics constraints. The COVID-era supply chain crisis exposed the risks of long lead times, limited supplier alternatives and transportation bottlenecks. When demand shifted sharply and shipping networks became congested, companies struggled to get essential goods where they were needed.
The subsequent period brought a different lesson: carrying too much inventory can become expensive when demand normalizes. Businesses that had built large buffers or committed to more space than they needed faced pressure to clear stock and reduce costs.
The current environment brings both lessons together. Companies still need protection against disruptions, but they also need the flexibility to scale down when demand softens.
The September 2026 LMI does not establish that a crisis on the scale of 2020 is underway. It does, however, show a measurable mismatch between expanding inventory and contracting warehouse and transportation capacity. The historical comparison is useful as a warning about the costs of overreaction, not as a prediction that the same events will repeat.
The more durable response is to use better data, selective buffers, alternative suppliers and flexible logistics contracts rather than relying on either minimal inventory or blanket stockpiling.
What Happens Next: The Signals Businesses Should Watch
The next stage depends on how quickly inventory moves from wholesalers and distributors to retailers, how much consumer demand materializes and whether logistics capacity improves.
Several indicators deserve close attention over the coming weeks:
- The next Logistics Managers’ Index release: Watch whether inventory growth continues and whether warehouse and transportation capacity remain in contraction.
- Warehouse utilization and pricing: Persistent pressure could make it more expensive to secure last-minute space.
- Transportation prices and capacity: Higher prices alongside continued contraction would signal that shippers have less room to negotiate.
- Import volumes and port activity: Strong inbound flows can add pressure if goods arrive faster than distribution networks can process them.
- Retail sales and consumer confidence: These help companies judge whether existing inventory is likely to sell through or become excess stock.
- Supplier lead times and tariff announcements: Changes may affect both purchasing schedules and landed costs.
The September LMI was released on October 6, 2026. The official LMI website publishes the monthly report and provides a useful reference point for tracking whether the pressure is easing or intensifying.
For logistics leaders, the practical takeaway is to prepare for several outcomes. If demand remains strong, companies will need reliable storage and transport to move stock through the network. If demand weakens, they will need to reduce replenishment and manage excess inventory without accumulating unnecessary costs.
Conclusion: Inventory Is Only an Advantage If Businesses Can Move It
The September 2026 logistics data points to a clear challenge for U.S. businesses: inventory is growing, but the capacity to store and move it is tightening. With the Logistics Managers’ Index at 70.2, warehouse capacity at 39.3 and transportation capacity at 34.4, companies are entering a critical seasonal period with less flexibility across key parts of the supply chain. Source: September 2026 Logistics Managers’ Index
Businesses cannot eliminate every tariff, demand or freight risk. They can, however, make better decisions about which products to stock, when to place orders, where to hold inventory and how to diversify suppliers.
The strongest response is to connect inventory planning directly to warehouse and transportation capacity. That means reserving flexible space early, using realistic demand scenarios, measuring the full cost of inventory and maintaining supplier alternatives for products that matter most.
As holiday demand moves through the network, the companies best positioned to protect margins will not necessarily be those with the most inventory. They will be the ones that can move the right inventory efficiently, adapt when conditions change and avoid paying for stock they cannot sell.
FAQ: U.S. Supply Chain Pressures
1. Why are U.S. supply chain pressures increasing in 2026?
The September 2026 Logistics Managers’ Index rose to 70.2 as inventory levels grew while warehouse and transportation capacity contracted. That combination can make it more difficult and expensive for companies to store goods and move them to customers before peak season.
2. What does a Logistics Managers’ Index reading of 70.2 mean?
The LMI is a diffusion index that measures changes across several logistics indicators. A reading above 50 indicates expansion, while a reading below 50 indicates contraction in the metric being measured. The overall reading of 70.2 signals rapid expansion in logistics activity, not that every component of the supply chain is expanding.
3. Why are warehouse capacity and transportation capacity tightening?
Growing inventories require more storage, receiving, handling and outbound shipping. Seasonal demand can concentrate those needs into a short period. In September, the LMI recorded warehouse capacity at 39.3 and transportation capacity at 34.4, both in contraction territory.
4. How do tariffs affect inventory planning?
Tariff uncertainty can encourage businesses to order earlier, change suppliers or shift sourcing locations. However, early purchasing can increase storage and financing costs. Companies should compare multiple tariff scenarios and calculate total landed cost rather than making decisions based on one expected policy outcome.
5. How can companies prepare for holiday supply chain disruptions?
Businesses can segment inventory by importance, update demand forecasts, confirm inbound and outbound schedules, reserve flexible warehouse space and arrange transportation early. Regular reviews of supplier lead times and warehouse utilization can help identify problems before they disrupt customer deliveries.
6. Does supplier diversification always reduce risk?
No. Diversification can reduce dependence on a single supplier or region, but alternative suppliers may have different quality standards, costs, lead times and capacity constraints. Companies should qualify backup sources in advance and verify that they can deliver during a disruption.
7. What is the best way to avoid excess inventory after the holidays?
Use demand scenarios, staged purchasing and frequent inventory reviews. Set clear triggers for slowing replenishment, transferring stock, markdowns or releasing temporary warehouse space. This helps reduce the risk of carrying expensive inventory after seasonal demand fades.
8. Which supply chain metrics should businesses monitor most closely?
Useful metrics include inventory days on hand, forecast accuracy, supplier lead-time variability, warehouse utilization, on-time delivery, freight cost per unit and aged inventory. Together, these measures show whether inventory is available, affordable to hold and likely to reach customers on time.
Sources & References
1. September 2026 Logistics Managers’ Index Report, Logistics Managers’ Index. Primary source for September index readings and commentary on inventory, warehouse capacity and transportation conditions.
2. The Source Market Update: October 2026, Source Logistics, October 7, 2026. Analysis of holiday inventory movement, warehouse capacity, freight pricing and retail readiness.
3. Transportation Prices Surge as Capacity Tightens Further in September, FreightWaves, October 6, 2026. Reporting on transportation prices, inventory levels and capacity constraints.
4. Report: Supply Chain Pressures Could Keep Prices Higher for Consumers, Florida Atlantic University, October 13, 2026. Research summary on inventory growth, logistics capacity and potential cost pressure.