
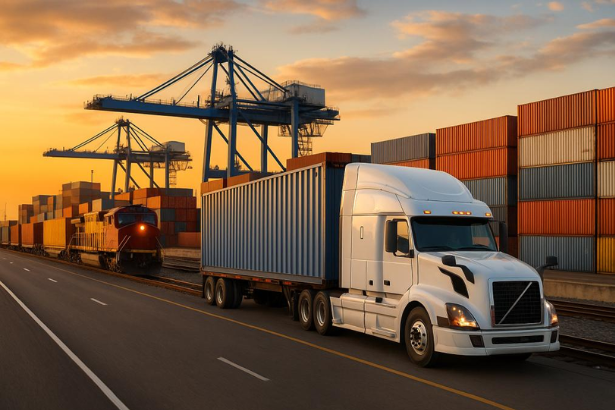
U.S. logistics trends Q4 2026 point to a freight market that is active but far from predictable. Demand remains steady, imports are strong and intermodal shipping is gaining ground against traditional truckload transportation. At the same time, high diesel prices, shifting capacity and uncertainty around consumer demand are putting pressure on logistics budgets.
FreightWaves’ October State of the Industry report, published in partnership with Ryder, describes a market where volumes and rates can change quickly. The report highlights domestic intermodal volumes running nearly 9% above the same period last year, while strong activity at major U.S. ports is keeping transportation networks busy. Fuel costs and weakness in housing-related freight remain important risks. Read the FreightWaves report. <Cite refs={[“turn136477search0”]}/>
For logistics leaders, the message is clear: Q4 planning should not rely on one freight-rate assumption or one transportation mode. Companies need to monitor lane-level costs, protect capacity for critical shipments and identify where rail, truckload and other options can work together.
Background and Context: Why Q4 Matters for U.S. Logistics
The fourth quarter is traditionally a demanding period for U.S. logistics. Retailers prepare for holiday sales, importers manage inventory, and carriers handle changing volumes across ports, warehouses, distribution centers and highways.
This year, that seasonal activity is meeting a market with competing signals. Strong imports and resilient consumer spending are supporting freight demand, but elevated fuel costs increase the cost of moving goods. Housing-related weakness is also weighing on construction freight, while uncertainty about consumer sentiment could affect demand later in the quarter.
The result is not a simple boom or downturn. Some routes and freight categories are busy, while others face softer demand or more difficult economics. Companies that plan around national averages alone may miss important differences between lanes, regions and shipping modes.
The FreightWaves report offers a useful snapshot of these conditions across trucking, maritime and intermodal markets. It is a sponsored industry report, so its findings should be considered alongside other sources, including government fuel data and port statistics. <Cite refs={[“turn136477search0″,”turn136477search3”]}/>
Latest Update: Five U.S. Logistics Trends to Watch in Q4 2026
1. Freight demand is steady, but the market remains fragile
FreightWaves reports that freight demand remains steady, while post-Labor Day volatility shows how quickly capacity and pricing can change. That distinction matters for shippers planning the rest of the year.
Steady demand does not mean every carrier has equal access to freight or that rates will remain stable. A sudden shift in shipment volumes, regional capacity or operating costs can change the economics of a lane with little warning.
For logistics teams, the practical response is to review forecasts frequently, maintain relationships with multiple qualified carriers and avoid relying on a single rate assumption for the entire quarter. Contracted capacity can support predictability, while carefully managed spot-market options may help address unexpected demand.
2. Diesel costs are putting pressure on transportation budgets
Fuel remains one of the most visible cost pressures in U.S. freight. The U.S. Energy Information Administration reported an average on-highway diesel price of $6.199 per gallon for the week of October 5, 2026, down from $6.382 the previous week. The price series shows how quickly fuel expenses can move, even when the weekly average eases. Check the EIA’s weekly diesel data. <Cite refs={[“turn136477search3”]}/>
For trucking companies, diesel affects operating costs directly. For shippers, the impact may appear through fuel surcharges, carrier pricing and changes in the relative cost of different routes.
Businesses should review how fuel surcharges are calculated, how frequently they are updated and whether their transport contracts clearly define the fuel-price index used. Comparing base rates without accounting for fuel can give an incomplete picture of the total cost of a shipment.
3. Major U.S. ports are handling strong import volumes
Port activity is another important signal for the quarter. Reuters reported that the Port of Los Angeles handled approximately 1.04 million twenty-foot equivalent units (TEUs) in September 2026, setting a monthly record. The report attributed the activity to factors including holiday shipments, route changes and importers adjusting their sourcing and shipping plans. Read Reuters’ report on the September port record. <Cite refs={[“turn136477search52”]}/>
High import volumes create opportunities for drayage operators, rail providers, warehouse operators and domestic freight carriers. They also make coordination more important. Containers must move from terminals to warehouses and distribution centers, often under tight appointment windows and equipment constraints.
Importers should plan beyond the ocean arrival date. Drayage availability, chassis access, terminal conditions, warehouse receiving capacity and inland transportation can all affect how quickly cargo reaches its destination.
4. Intermodal shipping is gaining ground against truckload
One of the strongest findings in the FreightWaves October report is that domestic intermodal volumes are running nearly 9% above the same period last year. The report points to cost savings and network efficiencies as important reasons for the mode’s strength. <Cite refs={[“turn136477search0”]}/>
Intermodal transportation combines rail with truck movement, typically using trucks for the first and final legs and rail for the long haul. It can be an attractive option for shipments that do not require the speed or flexibility of an all-truck service.
That does not mean rail is automatically the better choice. Intermodal performance depends on origin and destination access, terminal schedules, transit-time requirements, equipment availability and service reliability. Shipments with narrow delivery windows or frequent route changes may still favor truckload.
The best opportunity is to identify freight that can tolerate a different transit profile. Shippers can compare all-in cost and service performance by lane, then shift suitable volume instead of making a blanket change across their networks.
5. Manufacturing supports freight, while housing remains a drag
FreightWaves identifies manufacturing as a positive contributor to freight demand, citing continued expansion in factory orders, industrial production and transportation-equipment orders, although growth is moderating. The report also notes that housing remains a drag, with weaker home sales, housing starts and builder sentiment weighing on construction-related freight. <Cite refs={[“turn136477search0”]}/>
These differences matter because logistics demand is tied to what industries produce, sell and build. Industrial freight may support certain truckload, flatbed and intermodal lanes even while construction-related shipments are softer.
Carriers and brokers should monitor the industries served by their networks rather than treating freight demand as a single national trend. Shippers, meanwhile, can use sector-specific forecasts to refine inventory, inbound freight and capacity plans.
Expert Insights and Analysis: The Best Mode Depends on the Lane
The most useful takeaway from the current freight market is that transportation decisions need to become more specific. A national rate trend can provide context, but the economics of a shipment depend on its origin, destination, distance, timing, equipment requirements and service expectations.
Three operating priorities stand out.
Build a total-cost view. Compare base transportation rates alongside fuel surcharges, accessorial fees, detention, drayage, terminal charges and the cost of late deliveries. A lower quoted rate may not produce the lowest total cost if it creates delays or additional handling.
Use intermodal selectively. The reported year-over-year increase in domestic intermodal volumes makes it worth reviewing lanes that have stable origins and destinations and enough schedule flexibility. Start with a controlled set of lanes, measure on-time performance and compare total cost before expanding.
Plan for volatility instead of trying to predict every move. Maintain visibility into shipment status, carrier performance and upcoming capacity needs. Use multiple scenarios for fuel costs and shipment volumes, and establish decision thresholds for when to switch modes or secure additional capacity.
These are operational recommendations based on the market signals in the report, not guarantees that rates will rise or that intermodal will outperform on every route.
Broader Implications: Logistics Planning Is Becoming a Cost-Control Discipline
In Q4, logistics performance will affect more than the transportation budget. Freight delays can disrupt production schedules, reduce inventory availability and leave retailers with less time to replenish popular products. Conversely, moving goods too early or holding excess inventory can tie up working capital and warehouse space.
This makes coordination between procurement, logistics, warehouse operations and finance increasingly important. Transportation teams need to understand when a shipment must arrive, what inventory is already available and how much flexibility exists in the delivery schedule.
Strong port activity also highlights the importance of inland logistics. Ocean freight is only one part of the journey. A container that arrives at the terminal still needs to be collected, transported, received and processed. If drayage or warehouse capacity is constrained, the entire supply chain can feel the delay.
Internal link suggestion: Link the phrase “freight cost optimization strategies” to a relevant logistics cost-management or transportation-planning article on The Tech Marketer. Replace the homepage URL with the exact published article link before publication.
Related History: From Truckload-First Networks to Multimodal Planning
Many U.S. freight networks have traditionally relied heavily on trucking because it offers flexible routing and door-to-door service. Rail and intermodal have long served as alternatives for suitable long-haul shipments, particularly where volumes and routes support efficient rail movement.
When capacity tightens or truckload costs rise relative to rail, intermodal becomes more attractive. But the decision has never been based on price alone. Terminal access, transit times, schedule consistency, equipment availability and the cost of additional handling all influence whether a shipment should move by truck or rail.
The current intermodal trend is another example of companies reassessing transportation choices as market conditions change. Rather than replacing trucking, intermodal can complement it by giving logistics teams another option for the right freight.
The same principle applies to logistics technology. Better tracking, forecasting and transportation-management systems can help teams identify suitable lanes, compare carrier performance and make changes earlier. Technology is most valuable when it supports practical decisions rather than simply producing more dashboards.
What Happens Next?
Several indicators will help logistics teams understand how the U.S. market develops through the rest of Q4:
- Diesel prices: Follow the EIA’s weekly series to monitor changes in the fuel-cost environment.
- Port volumes: Watch monthly data from major gateways, especially if import demand remains strong.
- Intermodal volumes: Compare current activity with the same period last year and assess available service capacity.
- Truckload rates and capacity: Monitor lane-level quotes, tender rejections and carrier availability rather than relying only on national averages.
- Industry demand: Track manufacturing, housing and retail indicators that may influence different freight categories.
- Service performance: Measure on-time delivery, dwell time, detention and cost per shipment alongside transportation rates.
The main planning question is not whether all freight costs will rise or fall. It is which lanes are most exposed to fuel, capacity or volume changes, and which alternative plans are practical if conditions shift.
Conclusion
U.S. logistics trends in Q4 2026 point to a market with steady demand, strong import activity and growing interest in intermodal shipping, but also meaningful cost and capacity risks. Diesel prices remain an important budget variable, port records are increasing the need for reliable inland movement, and industry-specific demand is creating a mixed picture across freight categories.
For shippers and carriers, the strongest response is disciplined planning. Review lane-level economics, compare modes using total cost and service performance, and keep capacity plans flexible enough to handle changing demand. In a market where conditions can shift quickly, better decisions may matter more than any single freight-rate forecast.
FAQ
What are the biggest U.S. logistics trends for Q4 2026?
Key trends include steady but fragile freight demand, elevated diesel costs, strong import activity at major ports, growing domestic intermodal volumes and mixed demand across manufacturing and housing-related freight.
Are U.S. freight rates expected to rise in Q4 2026?
The market signals point to upward cost pressure from fuel and potential capacity changes, but they do not establish a single outcome for every lane. Actual rates depend on route, equipment, demand, carrier availability and contract terms.
Why is intermodal shipping gaining attention?
FreightWaves reports that domestic intermodal volumes are running nearly 9% above the same period last year. Cost savings and network efficiency can make intermodal attractive for suitable long-haul shipments, although service requirements and terminal access still matter.
How do diesel prices affect logistics costs?
Diesel affects carrier operating expenses and can influence fuel surcharges and quoted transportation rates. Shippers should review how fuel surcharges are calculated and compare the full cost of a shipment rather than the base rate alone.
What do high port volumes mean for U.S. logistics companies?
High import volumes can increase demand for drayage, rail, warehousing and inland trucking. They also increase the need to coordinate terminal pickup, equipment, appointments and warehouse receiving capacity.
How should shippers prepare for Q4 freight volatility?
Shippers can monitor lane-level rates, maintain relationships with multiple carriers, evaluate intermodal for suitable routes, model fuel-cost scenarios and coordinate transportation plans with inventory and warehouse capacity.
Is intermodal always cheaper than truckload?
No. Intermodal can offer savings on suitable routes, but the full comparison should include drayage, terminal handling, transit time, reliability and the cost of delays. The right choice depends on the shipment and service requirements.
Sources & References
- FreightWaves, “White Paper: State of the Industry – October 2026.” October 1, 2026. Read the report.
- U.S. Energy Information Administration, “Retail Prices for Diesel (On-Highway) – All Types.” Weekly data. View diesel price data.
- Reuters, “Port of Los Angeles sets September volume record, executive director says.” October 9, 2026. Read the report.
- Intermodal Association of North America, “U.S. Intermodal Freight Volume Remains Elevated in October.” October 8, 2026. Read the update.