
Rising transportation costs are forcing American manufacturers and shippers into decisions that were unthinkable just two years ago, from abandoning long-haul trucking for rail to watching the Pentagon spend billions stockpiling raw materials the country can no longer reliably source on its own. Two separate but connected stories surfaced this month that together paint a picture of a supply chain under real strain: freight economics are flipping in favor of railroads, and the Defense Logistics Agency has committed $2 billion to building a safety net against critical mineral shortages.
Latest Update
Freight data from the past few weeks shows a clear divergence in how transportation costs are hitting different parts of the supply chain. Rising fuel prices and freight rates are putting pressure on corporate supply chains, but sharply with different consequences: higher costs for automakers, a competitive opening for railroads and an unexpected advantage for some U.S. refiners caught in the middle of the shift. freightwaves
Diesel prices sit at the center of the story. Record fuel prices are pushing freight off U.S. roads, with diesel hitting a record high recently. That record, according to Detroit News reporting, landed in September. Diesel, a key cost for freight carriers, reached a record $6.53 per gallon in September, according to AAA data, a number that reshaped routing decisions almost overnight for shippers who had relied on trucking for speed and flexibility. detroitnews
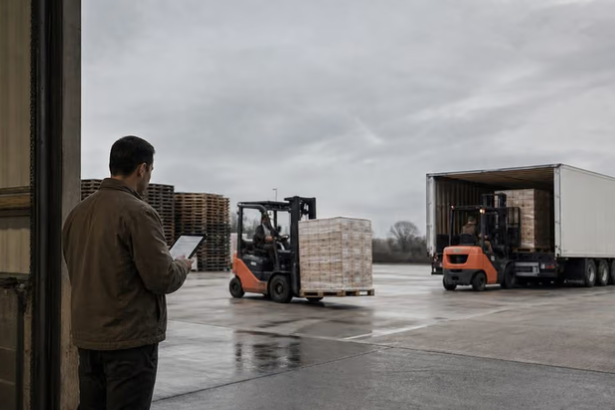
Railroads are the clearest beneficiary of that shift. The shift gives railroads a chance to win back long-haul freight from trucks, though higher fuel prices are raising their own costs and squeezing margins as geopolitical tensions keep fuel elevated. Executives at major rail carriers are framing this moment as a structural opening rather than a temporary blip, with one logistics consultant noting that long-haul truckload traffic is increasingly shifting to intermodal and rail-served distribution centers. spokesman
The mechanics of why rail wins when diesel spikes are straightforward. Railroads are much more efficient and cost way less per ton to move products across the country compared to trucks, which is precisely why shippers reach for rail the moment truck capacity tightens or fuel costs climb. That efficiency gap does not disappear when fuel prices eventually ease, but it becomes far less urgent, which is why the industry describes these shifts as cyclical rather than permanent.
Not every part of the shift is bad news for truckers. Diesel prices are declining in mid-November even as freight rates continue rising, a divergence that complicates the usual story of fuel costs driving freight economics. Higher transportation costs are still putting pressure on the businesses that depend on trucking, even as independent carriers see rates tick upward, because rising rates do not automatically translate into stronger profits once fuel, insurance, and capacity costs are factored in.
The Minerals Side of the Equation
While freight costs reshape how goods move, a parallel story is unfolding around what raw materials are available to make those goods in the first place. The Defense Logistics Agency announced on November 6 that it had committed $2 billion to acquiring critical minerals for the National Defense Stockpile during fiscal year 2026, the government’s reserve of raw materials held for national emergencies.
The money did not appear out of nowhere. Congress expanded the stockpile’s budget sharply in July 2025, when the One Big Beautiful Bill Act appropriated $2 billion to the National Defense Stockpile Transaction Fund, with the funds available through fiscal 2029. That legislative groundwork is now translating into actual contracts with suppliers of tungsten, cobalt, rare earths, titanium, and antimony.
One contract in particular illustrates both the scale of the push and the limits of what money alone can fix. In September, tungsten manufacturer The Elmet Group won a Defense Logistics Agency contract worth up to $2 billion to supply tungsten ores, concentrates, and sodium tungstate to the National Defense Stockpile, though only $150 million of that is guaranteed. The United States has not commercially mined tungsten since 2015, when cheaper imports undercut domestic production, and its net import reliance for the metal exceeded 50% as of 2025.
That dependency gap is exactly what the stockpile program is designed to address, but officials are clear that most of these contracts function as demand signals rather than instant fixes. Most of the agency’s critical mineral contracts are aimed at supporting domestic production by giving U.S. suppliers a clearer idea of what the government will buy, according to the director of DLA Strategic Materials, rather than solving the supply gap in a single fiscal year.
The scale of ambition is only growing. The Pentagon’s Defense Logistics Agency committed $2 billion in fiscal 2026 to the stockpile and has already requested $18 billion for fiscal 2027, a nine-fold jump that signals Washington expects this to be a multi-year, multi-billion-dollar undertaking rather than a one-time catch-up purchase.
Why These Two Stories Belong Together
Freight economics and mineral stockpiling look like unrelated stories until you follow the money through a factory’s cost structure. A manufacturer facing rising transportation costs for moving finished goods is often the same manufacturer facing rising input costs for the raw materials, many of them imported, that go into those goods. Both pressures compress margins from opposite ends of the production process.
There is also a timing overlap that matters for anyone running procurement or logistics. Diesel prices and freight capacity swing on a cycle measured in months, but mineral supply chains, especially for tungsten and rare earths, take years to rebuild domestically. Companies that are only reacting to this quarter’s freight bill risk missing the slower-moving mineral story that will shape sourcing decisions well into the next decade.
A further complication is emerging on the demand side of the minerals market itself. The Pentagon’s stockpile is not the only buyer competing for the same tight pool of critical minerals, since a new commercial reserve called Project Vault is filling its own warehouses from the same small markets at the same time, raising the real possibility of a bidding war between government and private buyers for materials that are already scarce.
Broader Implications
For supply chain and logistics teams, the practical takeaway is that cost pressure is no longer a single-lever problem. Freight mode decisions, fuel hedging, and mineral sourcing now have to be planned together rather than managed by separate departments reacting to separate headlines. Companies that treat rail conversion and mineral diversification as one connected resilience strategy, rather than two unrelated line items, are better positioned for whatever the next price shock looks like.
The Tech Marketer covers these intersections of logistics economics, federal procurement, and industrial supply chains as they develop, because the decisions being made in freight contracts and stockpile bids today will determine which manufacturers absorb the next cost shock and which ones pass it along. For ongoing coverage of how transportation and materials pressure is reshaping US manufacturing and logistics strategy, more analysis is available at The Tech Marketer.
The policy dimension is not going away either. With $18 billion requested for fiscal 2027 stockpile purchases, procurement teams across the defense industrial base and adjacent manufacturing sectors should expect federal buying activity to become a larger factor in mineral pricing and availability over the next two to three years.
FAQ
1. Why are transportation costs rising in 2026?
A combination of record diesel prices, tightened trucking capacity, and new regulatory enforcement has pushed freight rates higher, prompting many shippers to shift freight from trucks to rail.
2. Are railroads gaining business because of rising transportation costs?
Yes. Railroads are winning back long-haul freight from trucking as diesel costs climb, since rail remains significantly cheaper per ton to move goods across long distances.
3. What is the Defense Logistics Agency’s $2 billion stockpile for?
The DLA committed $2 billion in fiscal 2026 to buy critical minerals like tungsten, cobalt, and rare earths for the National Defense Stockpile, a reserve meant to cover shortfalls during national emergencies.
4. How is the US addressing its rare earth and critical mineral dependency?
Through stockpile contracts that act as demand signals to domestic suppliers, alongside a new commercial reserve called Project Vault, though officials acknowledge rebuilding domestic mining and processing capacity will take years.
5. Will rising transportation costs and mineral shortages affect manufacturers long term?
Both pressures are expected to persist for different reasons. Freight costs may ease if fuel prices drop, but mineral supply gaps require years of domestic investment to resolve, making them a longer-term planning concern.
Sources and References
- FreightWaves — Rising Q3 transportation costs squeeze manufacturers, reward railroads and reshape trade
- Detroit News — Railroads pull ahead as high fuel costs hit truckers harder
- Northern Miner — US reports $2B in mineral stockpile commitments
- Fortune — Pentagon’s war stockpile plan hits a minerals wall